Enrollment Confusion: This year's health insurance sign-up window is the messiest in years
November 2026
A big ball of uncertainty.
According to local experts, that’s what this year’s health insurance enrollment period is shaping up to be, thanks to a series of recent changes to federal law. The tweaks – which impact Medicaid, Medicare and the HealthCare.gov marketplace – will make this season more of a headache than usual for benefits professionals. But what do these changes mean for you? Read on to find out.
December 15 or January 15?
Anyone who buys their health coverage through the HealthCare.gov marketplace is likely familiar with the typical open enrollment period of November 1 through January 15. From 2022 to 2026, this two-and-a-half-month window was the standard time allotment for buying insurance through the federal marketplace.
Then, last year, a federal rule upended this norm. The new standard, called the 2025 Marketplace Integrity and Affordability Final Rule, set multiple new provisions for the Affordable Care Act, including a significant one impacting enrollment periods.
Specifically, the rule dictated that all health insurance policies purchased through HealthCare.gov must begin coverage on January 1. As part of that requirement, the rule stipulated that the open enrollment period for the federal marketplace must now run from November 1 through December 15, beginning this year.
Here’s where the uncertainty comes in, though: In June, a federal judge vacated large parts of the Marketplace Integrity rule, including the abbreviated ACA enrollment window. The Trump administration has appealed that ruling, but as of this writing, the old November 1 through January 15 open enrollment period still stands.
The implications
Just how big of a win is keeping that extra month of enrollment time?
According to insurance experts, less than you might think.
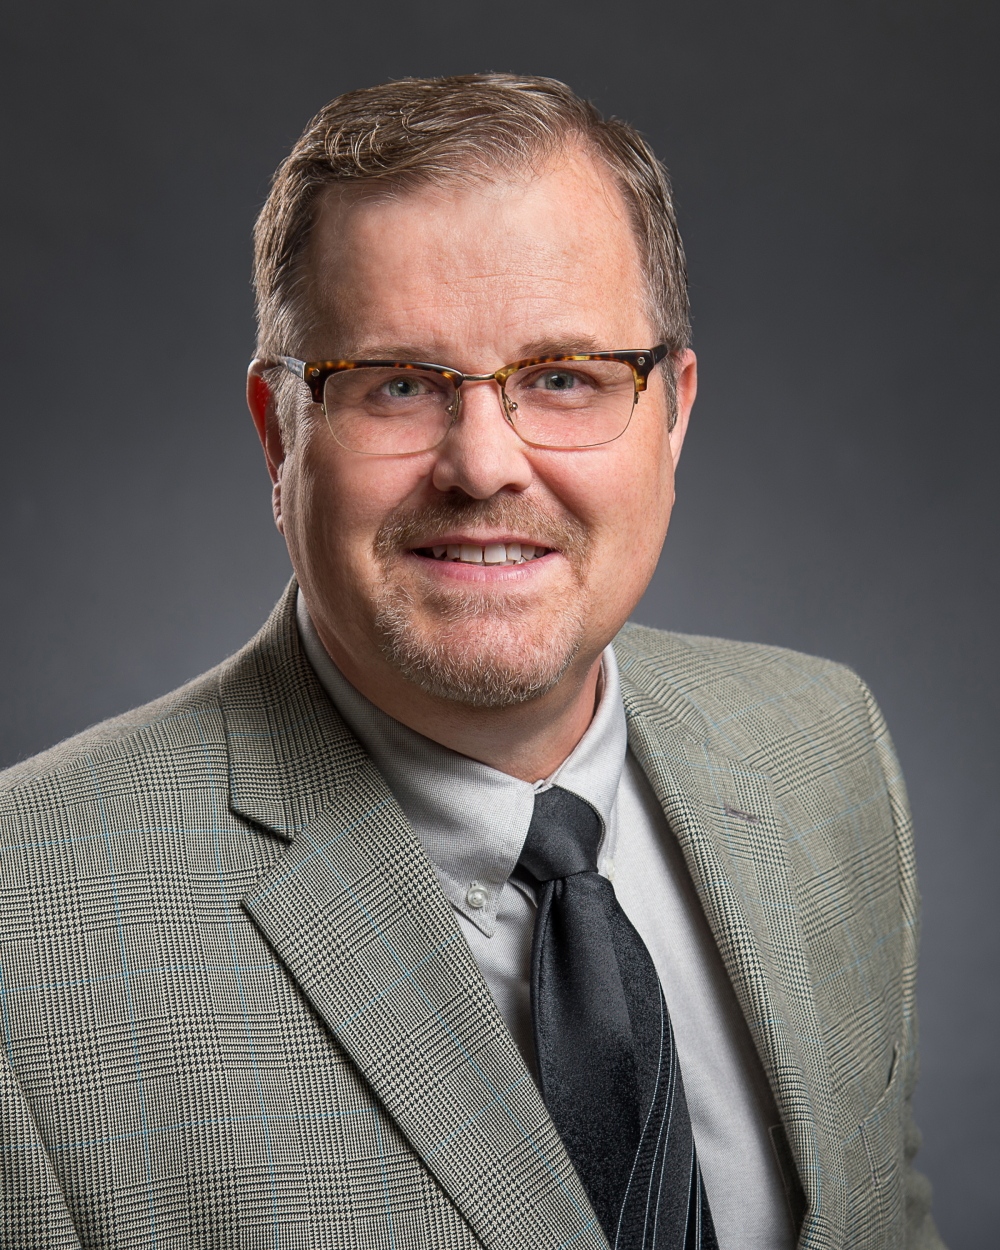 Andrews
David Andrews, an agent at local insurance agency InsureTC, says the ACA marketplace originally had an enrollment period that ran through February 15. The extra time, it turned out, came with baggage.
“Coverage would not start until March 1, and carriers felt that having several months for open enrollment would lead to adverse selection, which it did,” Andrews said. “The feds rolled it back in an attempt to keep the ACA affordable.”
While that rollback gave customers until January 15 to buy coverage, Andrews says it’s always been rare for one of his clients buying ACA coverage to stray into the New Year with their enrollment process.
“Clients have almost always had to enroll by December 15 if they wanted a January 1 effective date,” he explained. “If they wait until after December 15, they have until January 15 (to enroll), but they will have a February 1 effective date.”
Mark McLane, of Traverse City’s Mark McLane Insurance, concurs with Andrews. To avoid lapses in coverage, he says, almost all his clients that go through the HealthCare.gov marketplace want a January 1 effective date, which means a de facto December 15 enrollment deadline.
A complicated year
Still, if ever there was a year to avoid a date change that might throw unsuspecting customers for a loop, this is that year.
 Swartz
So says Kurt Swartz, a managing partner for Michigan Planners. Based in Washington, Michigan, the insurance business expanded to Traverse City 12 years ago, and now serves more than 160 group clients and 4,000 individuals out of its local office.
Historically, Swartz says individuals buying healthcare insurance on the marketplace are “not always the most organized.” Many are first-timers, taking the ACA route after eligibility or coverage through another platform – be it Medicaid or employer-provided insurance – lapses.
“They end up coming to us asking, ‘What do I do?’” Swartz said of those clients.
With significant upheaval in the health insurance world at the moment, Swartz expects this year – and likely the next few years – will see more customers dipping into the HealthCare.gov marketplace.
One factor is the rising cost of health insurance plans for employers.
“For multiple years in a row, employers have been facing average increases between 12% and 25%,” Swartz said. “The big challenge for employers right now is trying to wrestle with how to mitigate the increases without completely eroding the benefit.”
So far, Swartz says Michigan Planners has seen a “shockingly large amount of our clients absorbing these increases, because they say they just can't pass it on to their employees.” Instead, employers are looking for other ways to cut costs – such as “watering down deductibles or copays” – rather than shifting the cost of the premiums to their workers.
But after three years of “double-digit increases,” and with most forecasts indicating premium increases won’t even start to plateau until 2028, Swartz says the question is becoming one of tenability. Some employers are beginning to look at new cost-sharing models that put more of the cost burden on employees. Others are tasking for “outside-of-the-box solutions,” from partnering with direct primary care clinics like Traverse City’s Table Health, to “carving out drugs and having self-funded prescription drugs with different pharmacy benefit managers.”
“There’s a lot of interest in those kinds of alternatives,” Swartz said. “People are getting tired of the same old, same old.”
That curiosity about alternatives could also push some individuals to the HealthCare.gov marketplace for the first time, to check alternatives to their employer-sponsored plans.
Rising costs for employer-sponsored health plans are not the only factor driving people toward the marketplace. On the national level, last year’s One Big Beautiful Bill Act created a series of new eligibility requirements for Medicaid. The Robert Wood Johnson Foundation has since projected that between five and 10 million people will lose coverage by 2028, as a result of the Trump administration legislation.
 McLane
Additionally, Swartz says insurance carriers like Priority Health are in the process of “eliminating a majority of their Medicare Advantage plans, which is causing all of these seniors to have to re-enroll in the next in the next 60 to 90 days.”
With so much up in the air around insurance right now, Swartz is thankful that a shorter ACA enrollment window isn’t also clicking into place this year. One more change, he says, would be too much to deal with.
Not that a reimagining of the enrollment calendar would be the worst thing, according to McLane. He says the currently overlapping nature of the ACA enrollment window and the “annual election period” for Medicare (which runs from October 15 to December 15) often leads to an extremely harried fall season for insurance pros.
“I certainly wish that they would break up the open enrollment periods between Medicare and the Affordable Care Act,” McLane said. “I’m not the only health insurance agent that does both markets, and to have them overlap like that is difficult. If we were able to start the Medicare open enrollment period on September 15, close it on, say, November 7, and then have the ACA window start on November 1, that would make our lives a lot easier.”